When you look at bond yields, you may notice that bonds with similar maturities can still offer very different interest rates.
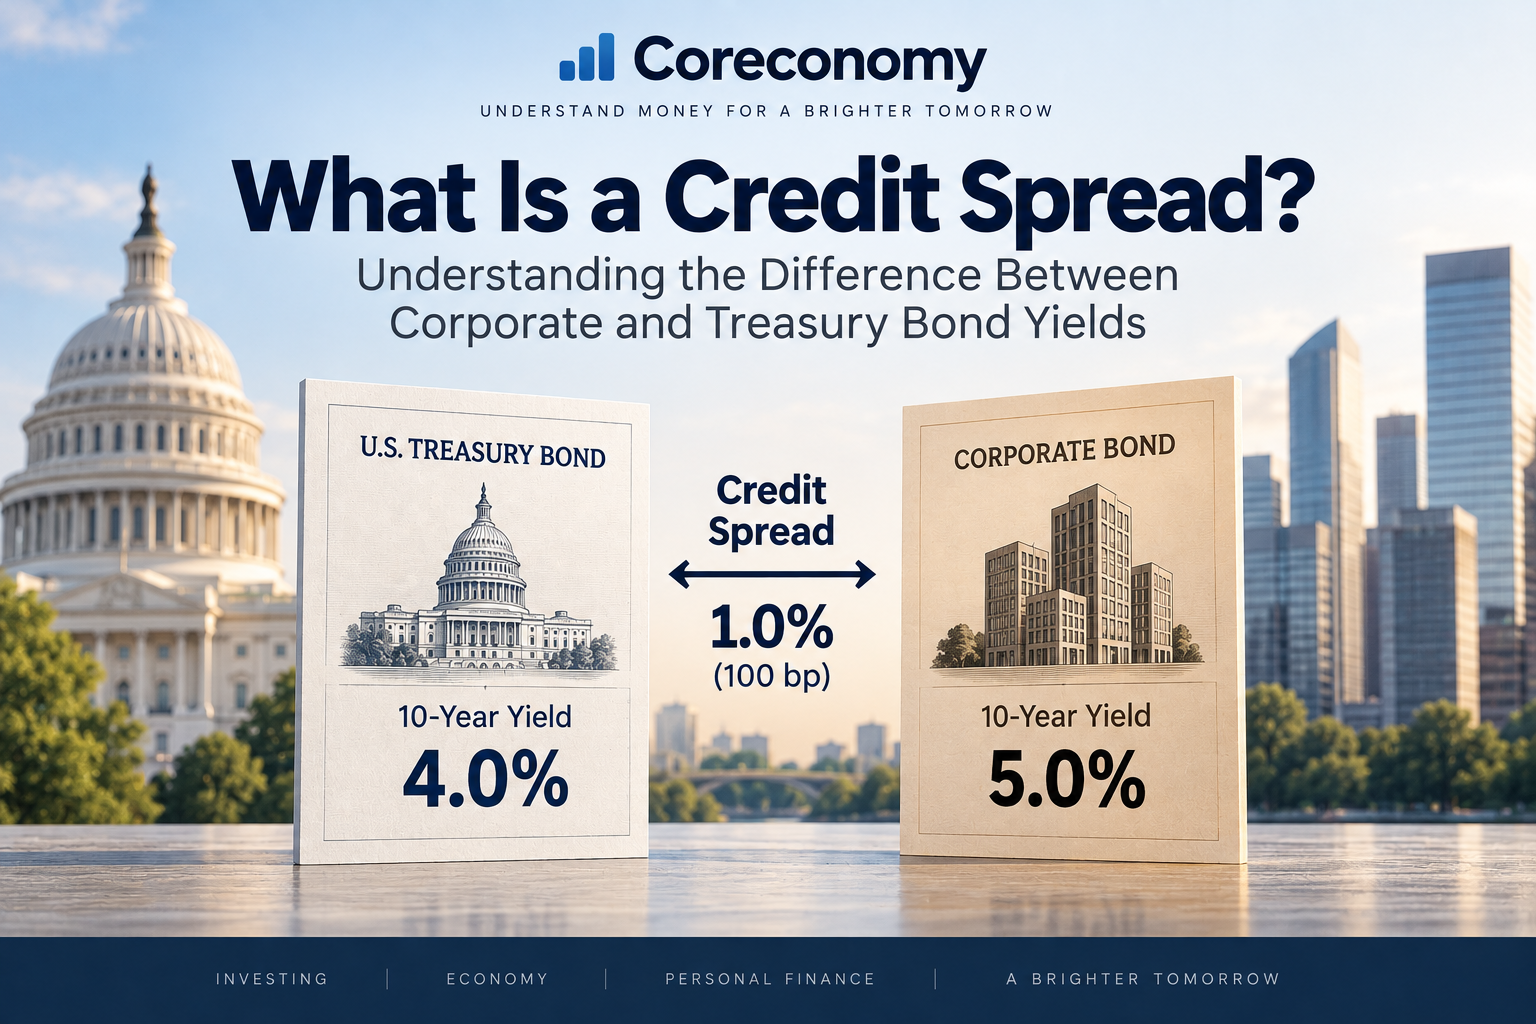
For example, suppose the 10-year U.S. Treasury yield is 4% while a 10-year corporate bond yields 5%.
The difference is 1 percentage point.
Why would investors demand a higher yield from one bond than another when both mature in 10 years?
One important reason is credit risk.
The U.S. government and a company are different borrowers, so investors may face different levels of risk when lending them money.
The difference in yield associated with this additional risk is captured by the concept of a credit spread.
In this article, we will explain what a credit spread is, why it exists, what it means when spreads widen or narrow, and how to interpret it as a beginner.
1. What Is a Credit Spread?
A credit spread is the difference in yield between a bond with higher credit risk and a relatively safer bond.
In simple terms,
A credit spread is the additional yield investors demand for taking on more credit risk.
For example, suppose:
- 10-year U.S. Treasury yield: 4%
- 10-year corporate bond yield: 5%
The difference is:
5% − 4% = 1 percentage point
In this simplified example, the credit spread is 1 percentage point.
Financial markets often express yield differences in basis points (bp).
Since:
1 percentage point = 100 basis points
a credit spread of 1 percentage point is the same as 100 basis points (100 bp).
So if you hear that a credit spread is 100 bp, it means the yield difference between the two bonds is 1 percentage point.
2. Which Bond Is Used as the Benchmark?
There is an important point to keep in mind.
You cannot simply pick any Treasury bond and subtract its yield from a corporate bond yield.
The comparison usually uses a relatively safe bond with a similar maturity and other relevant characteristics.
For example, if you are looking at the credit spread on a 10-year corporate bond, comparing it with a 2-year Treasury yield would not make much sense.
Instead, you would generally compare it with a Treasury yield around the 10-year maturity.
For example:
- 10-year U.S. Treasury yield: 4%
- 10-year corporate bond yield: 5%
The difference is 1 percentage point.
Why does maturity matter?
Because bond yields can differ depending on how long the money is being borrowed.
If you compare a 10-year corporate bond with a 2-year Treasury bond, the difference in yields may reflect not only credit risk but also the difference in maturity.
In real-world markets, a corporate bond may not have a maturity that exactly matches a Treasury maturity.
For example, a corporate bond might have 8.7 years remaining until maturity.
In that case, analysts may use the Treasury yield curve to estimate the Treasury yield corresponding to that maturity and make a more precise comparison.
So the basic idea to remember is:
A credit spread is not simply a corporate bond yield minus any Treasury yield. It is a comparison with a relatively safe benchmark that has similar characteristics.
3. Why Are Corporate Bond Yields Usually Higher Than Treasury Yields?
One important reason corporate bonds usually offer higher yields than Treasuries is credit risk.
A company has to generate enough cash from its business to pay interest and eventually repay its debt.
If the company’s financial condition deteriorates or the economy weakens significantly, the company may have more difficulty meeting its debt obligations.
Investors therefore may demand additional compensation for lending money to the company.
In general:
Higher credit risk → higher required yield → higher corporate bond yield
By contrast, a relatively safe bond may require less additional compensation for credit risk.
This means that a corporate bond’s yield can reflect not only compensation for lending money for a certain period of time, but also compensation for the possibility that the borrower may fail to repay its debt.
4. How Is a Credit Spread Calculated?
The basic calculation is simple:
Corporate bond yield − yield on the comparable safer bond
For example:
Example A
- 10-year Treasury yield: 4%
- 10-year corporate bond yield: 5%
→ Credit spread: 1 percentage point
Example B
- 10-year Treasury yield: 4%
- 10-year corporate bond yield: 6%
→ Credit spread: 2 percentage points
In both examples, the corporate bond offers a higher yield than the Treasury.
But the credit spread shows the difference more clearly.
In Example A, investors demand 1 percentage point of additional yield over the Treasury.
In Example B, they demand 2 percentage points.
This means the additional compensation required for holding the corporate bond is higher in Example B.
In actual financial markets, credit spreads can also be measured against other benchmark curves, such as swap rates, rather than directly against Treasury yields.
That is why it is important to check which bond and which benchmark are being compared when you see a credit spread quoted in financial data.
5. What Does It Mean When Credit Spreads Widen?
A credit spread widens when the yield difference between the higher-risk bond and the safer benchmark becomes larger.
For example, suppose:
- Treasury yield: 4%
- Corporate bond yield: 5%
- Credit spread: 1 percentage point
Later, the corporate bond yield rises to 6% while the Treasury yield remains at 4%.
Now:
- Treasury yield: 4%
- Corporate bond yield: 6%
- Credit spread: 2 percentage points
The credit spread has widened from 1 percentage point to 2 percentage points.
This may indicate that investors are demanding more compensation for taking on credit risk.
For companies, a wider credit spread can also mean a more expensive financing environment because they may have to offer higher yields when issuing new debt.
So a widening credit spread can be a sign that corporate borrowing conditions are becoming more difficult.
6. What Does It Mean When Credit Spreads Narrow?
A credit spread narrows when the yield difference between the higher-risk bond and the safer benchmark becomes smaller.
For example:
Before
- Treasury yield: 4%
- Corporate bond yield: 6%
→ Credit spread: 2 percentage points
Later
- Treasury yield: 4%
- Corporate bond yield: 5%
→ Credit spread: 1 percentage point
The spread has narrowed from 2 percentage points to 1 percentage point.
This means investors are demanding less additional yield from the corporate bond compared with the Treasury.
For companies, this can create a more favorable environment for raising debt because they may be able to borrow at a lower spread over the benchmark.
However, a narrowing credit spread does not necessarily mean that every company’s financial condition has improved.
Investor risk appetite may have increased, or concerns about financial markets may have eased.
In other words, market conditions can affect credit spreads as well as the financial health of individual companies.
7. How Are Credit Spreads Related to the Economy?
Credit spreads are often influenced by economic conditions.
When the economy is stable and corporate earnings are expected to remain healthy, investors may view the risk of companies failing to repay their debt as relatively low.
Demand for corporate bonds may increase, pushing their yields down relative to Treasury yields and causing credit spreads to narrow.
On the other hand, when concerns about an economic slowdown or recession increase, investors may become more concerned about corporate earnings and defaults.
They may demand higher yields to hold corporate bonds, causing credit spreads to widen.
A simplified way to think about the relationship is:
Improving economic outlook → lower credit risk concerns → credit spreads may narrow
Worsening economic outlook → higher credit risk concerns → credit spreads may widen
However, the economy is not the only factor that moves credit spreads.
Investor risk appetite, bond supply and demand, liquidity, and broader financial market conditions can also have a significant effect.
For this reason, it is better to look at credit spreads alongside other economic and financial indicators rather than using them alone to judge the direction of the economy.
8. Do Lower-Rated Bonds Have Larger Credit Spreads?
In general, companies with lower credit ratings are considered to have higher credit risk.
Credit ratings reflect an assessment of a company’s ability to meet its debt obligations.
Therefore, all else being equal, investors may demand a higher yield from a lower-rated company’s bonds.
For example:
Company A
- Higher credit rating
- Corporate bond yield: 5%
Company B
- Lower credit rating
- Corporate bond yield: 7%
Suppose the comparable Treasury yield is 4% and the bonds have similar maturities and other relevant characteristics.
Then:
- Company A credit spread: 1 percentage point
- Company B credit spread: 3 percentage points
Company B has a larger spread because investors require more compensation for taking on the additional credit risk.
This is why credit spreads are often analyzed across different credit rating categories.
9. How Is a Credit Spread Different From the Policy Rate?
It is also important not to confuse a credit spread with the policy rate.
The policy rate is a key interest rate set by a central bank as part of its monetary policy.
A credit spread, on the other hand, is a difference between two yields.
For example, suppose:
- Central bank policy rate: 4%
- Treasury yield: 5%
- Corporate bond yield: 6%
The difference between the corporate bond and Treasury yields is:
6% − 5% = 1 percentage point
So the credit spread is 1 percentage point.
It is not the 2-percentage-point difference between the policy rate and the corporate bond yield.
This distinction is important because corporate bond yields are influenced by many factors, including the policy rate, Treasury yields, credit risk, and investor risk appetite.
10. A Higher Corporate Bond Yield Does Not Necessarily Mean Higher Credit Risk
A corporate bond yield can rise even when the company’s credit risk has not increased.
The reason is that Treasury yields can rise at the same time.
For example:
Example A
- Treasury yield: 4%
- Corporate bond yield: 5%
- Credit spread: 1 percentage point
Example B
- Treasury yield: 5%
- Corporate bond yield: 6%
- Credit spread: 1 percentage point
In Example B, the corporate bond yield increased from 5% to 6%.
But the Treasury yield also increased from 4% to 5%.
As a result, the credit spread remained unchanged at 1 percentage point.
Simply looking at the increase in the corporate bond yield could therefore give the wrong impression.
When a corporate bond yield changes, it is important to ask:
Did the benchmark Treasury yield move as well?
This is one reason credit spreads are useful: they help us focus on the relative difference in yields between the corporate bond and its benchmark, rather than looking at the corporate bond yield alone.
11. What Should You Look at When Analyzing Credit Spreads?
When looking at a credit spread, it is better to consider several factors rather than focusing on a single number.
① Which bond does the spread refer to?
Not all corporate bonds carry the same level of credit risk.
Check which company, sector, or credit rating the spread represents.
② What is the benchmark?
The meaning of a credit spread depends on what it is being compared with.
Check whether it is measured against a comparable Treasury yield or another benchmark, such as a swap rate.
③ Has the spread widened or narrowed compared with the past?
The change in a credit spread can be more informative than its absolute level.
If spreads suddenly widen, it may be worth looking at whether corporate financing conditions or broader financial market conditions have changed.
④ Is it moving together with other economic indicators?
Credit spreads can be affected by economic conditions, interest rates, and investor sentiment.
Looking at Treasury yields, economic data, and broader financial market conditions together can provide a more complete picture.
Conclusion
A credit spread is the difference in yield between a bond with higher credit risk and a relatively safer benchmark bond.
The key points are:
- A credit spread measures the yield difference between riskier and safer bonds.
- The comparison should generally use bonds with similar maturities and relevant characteristics.
- Corporate bonds often offer higher yields because investors require compensation for credit risk.
- A widening credit spread can indicate that investors are demanding more compensation for taking on risk.
- A narrowing credit spread can indicate that the additional yield demanded for taking on risk has decreased.
- Economic conditions and investor risk appetite can affect credit spreads.
- A higher corporate bond yield does not necessarily mean that credit risk has increased.
- When analyzing a credit spread, it is important to know what benchmark is being used.
When looking at bond yields, simply asking “What is the yield?” does not tell the whole story.
Two bonds with similar maturities can offer different yields because investors face different levels of risk depending on who is borrowing the money.
A credit spread helps us understand how much additional yield investors are demanding for taking on that additional risk.
In this way, credit spreads provide a useful window into how the bond market is pricing credit risk and compensation for risk.